An interesting week watching what will happen in Greece. As ever, the markets move as if it will all be completed in a late-night stitch up on Thursday. All will be well in time for Saturday and the US has chipped in to say don't drop the ball and cause a crisis (irony alert - Lehman Brothers).
Meanwhile, perhaps for domestic consumption, the current Greek PM claims that all is not well and the international community are being big meanies -
"the obsession of some institutional representatives who insist on unreasonable solutions and are being indifferent to the democratic result of recent Greek elections"
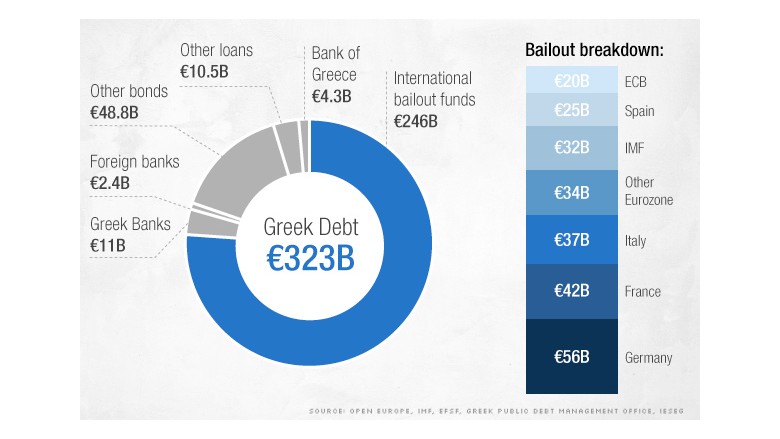
So says Tsipras, but who knows what he really means. What we do know is that the group of international lenders are being intransigent. There is no reasonable way that Greece could ever get its public debt back in order without a large write-off. For political reasons, the Germans don't want that to set a bad example for others. Also, as much as the Greeks hate the Troika they don't want to leave the teat of the EU.
The Greek Government was elected on a populist lie, a fine tradition in the failure of Greek politics, which it cannot deliver.
So either we will get -
- Greece forced by the EU and IMF to concede to endless Austerity. With no choice Tsipras and his Government will have to whip up severe anti-foreigner nationalism to try to dissemble away from reality.
- Greece not agreeing, as Tsipras finally gets the EU cares not one jot for Democracy - a messy Grexit ensues but of course Greece defaults and in 5 years will be a much better place that it is now.
On we go, tick, tock.
Showing posts with label IMF. Show all posts
Monday, 1 June 2015
Tuesday, 7 October 2014
Euro Crisis: Round 2
The papers today and tomorrow will be full of the story of the IMF reporting that Europe needs to follow the UK's lead on austerity and how wrong that have been to criticise the Government in the past.
However, they are all missing or will miss the two really key issues:
1) The UK has not undergone real austerity. The cuts in some areas have been made up by tax cuts and increases in other areas of spending such as Foreign Aid and the NHS. The IMF say the UK has obtained fiscal credibility - oddly, this is because the UK has engaged in a massive exercise in money printing. This could not have happened in the eurozone as the central bank will not do this.
2) Germany is rapidly falling towards recession, driven by a drop of exports to Russia and the continued downturn in its export markets around Europe and in China. With France and Italy not really out of recession, this means the Eurozone is heading back towards trouble. No growth and huge debts leave many of the Countries in the eurozone very exposed indeed.
2011 was not a pretty year, if 2015 repeats it then the UK is in for a tough time given our own debt dynamics.
Tuesday, 21 January 2014
IMF Upgrade for UK
It's always nice to see some real humble pie being consumed. As most readers will be aware, the UK remains in a parlous financial state, as does much of the Western world. The whole recovery will be de-railed sooner or later by the next stage of the Euro crisis and by the sheer unsustainability of the debts accrued across the West by their over-purchase of Chinese goods.
However, austerity is not the cause but offers partial solution. Better still would be the re-structure of the welfare state in the West along more Hobbesian lines, but for now that is incompatible with democracy. So austerity of some sort remains the best approach. The Coalition government at least did apply the brakes to Labour spending and after some time is now reaping the rewards with a more stable growth than has been achieved in say the US. The IMF were very quick to blame Osborne for his crazy (read, un-French) policies and now the UK is prediceted to be the fastest growing Western nation this year.
It must make for a little bit of extra spring in the Chancellor's morning jog today.
The real challenge lays on two fronts though. Firstly that there seems to be no political benefit to the 'hated' Tories for engineering a recovery - after all, it's what they said they would do. Secondly, with interest rates at 0.5% and QE in place, we are still deep in the middle of the woods with no clear path out yet identified.
Wednesday, 25 May 2011
IMF: Rebellion of the BRIC's
Interesting to see a rare grouping of the BRIC's in attacking the IMF and wanting to seize the crown. When one considers the history of the IMF, with its poor policies in the 80's that wrecked many a country and its perception (see picture) of being a Western tool for control of developing counties, this should be no surprise. The IMF is a tool of western imperialism in the minds of many of those on the receiving end of its policies.
One problem with this is that overall, the view expressed above is wrong. The IMF exists to save countries and often the worst that can be said about it is that in acting so late in the day, the problems have already overtaken he ability of a Country to cope - leading to default and mass austerity for the population. The IMF is an ambulance; the patient is already seriously wounded on arrival and emergency treatment is hazardous without guarantees pf success.
Now, though is a new century and with the Western powers themselves excruciatingly weak, it is a good time to strike. However, I doubt very much even if a non-European head was appointed that it would make much difference. The glamour of being an international civil servant and the mindset that goes with it will soon affect any incumbent (after all, in order to apply you need to be from this cadre already) - and it will be back to business as usual.
The worry must be for the Europeans who are trying to get the IMF to hep the Euro without agreeing fair terms - however, this is going to fail anyway as the European debt crisis spirals over the next few months and years.
Monday, 16 May 2011
Strauss-Kahn's perfect timing
Now, mr Dominique Strauss-Kahn is not someon you will find Capitalists defending in general. The communist Frenchman has a long hisotry of economic and political misjudgements. However, his arrest on Friday in New York is quite something.
At a crucial moment in the negotiations over further European bailout the key lead is gone. the IMF have bent over to help the EU, even though the EU has held tight onto its prinicples of keeping the Euro and avoiding default. In part, this has been thanks to the head of the IMF backing this unorthodox (read silly) strategy.
So to have the one of the lead actors incapacitated at such a key moment is intriguing. of course Strauss-Kahn was also going to stand for the French Presidency so he will have many enemies across the world - which does not mean that in the end, he is his own worst enemy after all.
His temporary replacement is an American with a background of working for JP Morgan. He is sure to have different views, although perhaps the needs of diplomacy mean that he won't be able to obviously change track on IMF policy too quickly; however, charges for Stauss-Kahn will mean Lipsky will get a more long-term shot at the job, certainly until new appointments in the new year.
Timing is everything and this timing sure seems 'odd', conspiracy theorists will have a field day but the key will be to see if there is any change to the terms of the Greek bailout - the more changes there are, the more suspicious I will become.
Wednesday, 24 February 2010
Why the IMF are wrong
The IMF have come out today with a report suggesting that Advanced Countries do not end financial stimulus (this is what our Prime Minister is addcited too, remember?) before 2011 for fear of causing a double dip recession.
No doubt the bullying left wing cheerleaders will say the Tories are wrong again. Where to start? Well firstly Dominique Strauss-Kahn who is the Frenchman who runs the IMF is a marxist and so will always think state spending is a good idea.
Secondly, George Osborne had a good phrase at the start of the crisis "You can't borrow your way out of a borrowing crisis." This is even more truwe today, even with sclerotic growth in the economy, piling up debts on top this shaky foundations is simply not the answer.
Thirdly, all this so called stimulus and Government spending is not economically beneficial. Quantitative Easing has been used to boost the bond and equity markets (good for those who foresaw this), which has bailed out the banks but done nothing to increase demand in the real economy. The Government spending on diversity counsellors, bullying hotlines and regional quangos' is of dubious value except to those who collect the paychecks. It would be much easier to scrap the lot of these jobs and then raise unemployment benefit by 80% of the savings made.
Finally, a double dip - where is the evidence in the UK that we have even exited recession? The UK is in a far worse position thanks to Labour overspending in the boom than France or Germany. We are simply not in a position to spend more of our children's money so frivolously.
So where do we get too? Well a sensible Chancellor would start cutting the fat off the public sector straight away, at least 5% a year for the next Parliament should do it. Quantitative Easing should not be re-started as it only piles up future losses. If the banks need more money they can raise it in the market like they did last year.
Monday, 27 October 2008
Ukraine goes to the IMF; who else is in line?

The post I did a a couple of weeks ago on RISK comes true. Now the Ukraine is seeking quite a lot of cash from the IMF to help stabilise its economy. This adds to Iceland, Hungary, Argentina and others.
As such there have been no big country casualties yet, Russia would have been but for its large FOREX reserves built up through the oil peak of the past couple of years.
The IMF has $200 billion to lend and seems to have committed roughly $30 billion so far. To me the interesting thing would be if a country such as the UK was forced to go and ask for a loan. The loan would be so enormous as to overwhelm the reserves of the IMF. Yet it also seems unlikely that this crisis will pass without some larger victims. After all, it is the banks and financiers in Western countries who drunk the sub-prime/CDO/LBO poison the most.
The IMF needs much more funding if it is to be the answer to this crisis and I am sure this is high on the agenda of the 15/9 meeting.
Also on the Risk theme, Sarkozy is running around the world declaring victory for French State-Capitalism - signing up the Asian nations in his 'war' with USA/UK 'Anglo-Capitalism.' An ideological world conflict between the advanced nations?
The outcome of all this will be most interesting, no one I meet is in favour of less financial regulation and co-ordination - but will the solution be a return to the failures of the past or a brave new world order?
Subscribe to:
Posts (Atom)